Search

College Budget: How to Plan Costs Before the First Semester

College Budget: How to Plan Costs Before the First Semester

A college budget is more than a spreadsheet. It is a shared plan for tuition, housing, food, transportation, books, personal costs, financial aid, work, and emergency expenses before the first bill arrives. For first-generation students and families, that plan can turn a stressful money conversation into a set of next steps.

The goal is not to predict every dollar perfectly. The goal is to understand the biggest costs, compare them across schools, identify gaps early, and decide who will handle which tasks. A strong budget helps students choose a college they can start, afford, and continue.

This guide walks through the money talk, the official numbers to review, and a practical student budget checklist families can use before orientation or move-in.

Early budgeting also improves the college-choice conversation. When students can see the monthly reality of each option, they can compare fit, affordability, transportation, work, and support before emotions or deadlines take over.

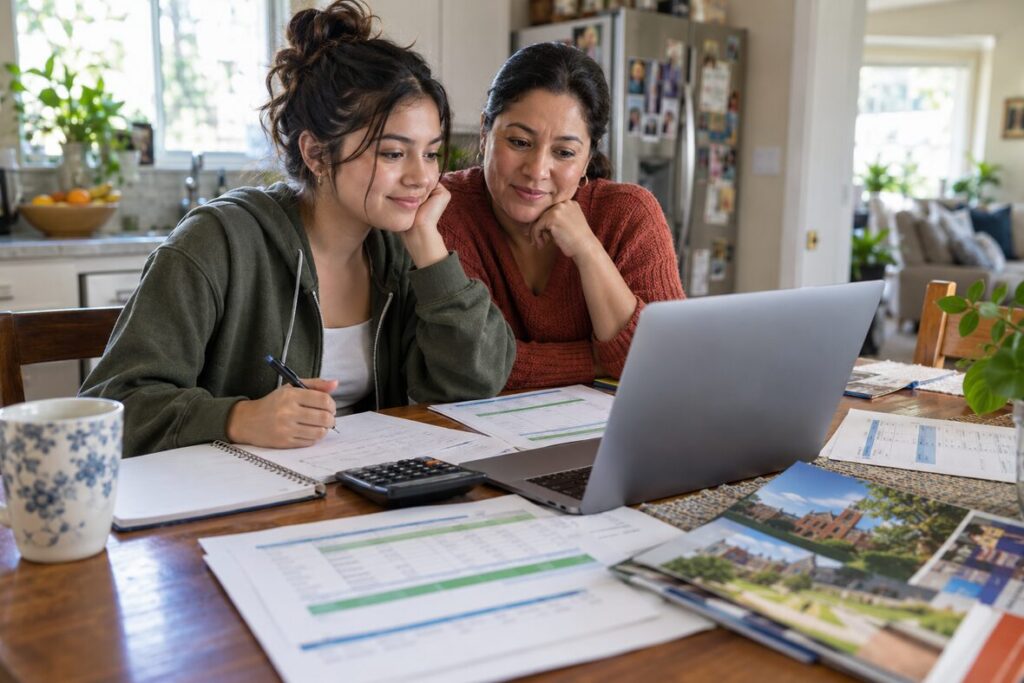
Student and parent reviewing scholarship spreadsheets and financial aid offers at a kitchen table

Start With Cost of Attendance

Every college publishes a cost of attendance, often called COA. Federal Student Aid explains that cost of attendance includes more than tuition and fees. It can include housing, food, books, supplies, transportation, loan fees, and personal expenses. That number is the starting point for a realistic college budget.

Families should not stop at the headline price. A student living at home, commuting, and using a meal plan will have a different budget from a student living on campus or renting near school. Print or save the COA for each college, then adjust the categories to match the student’s actual plan.

This is also where local details matter for GEO and practical planning. Transportation costs depend on bus routes, parking permits, gas, car repairs, campus location, and work schedules. Food costs depend on meal plans, grocery access, and whether the student goes home on weekends. A budget gets better when it is grounded in place.

Understand Aid Before You Compare Schools

After the FAFSA is processed, students receive information that colleges use to build aid offers. Families should review the FAFSA Submission Summary for accuracy, then compare financial aid letters side by side. Look for grants, scholarships, work-study, subsidized loans, unsubsidized loans, parent loans, and remaining balance.

The Consumer Financial Protection Bureau offers a financial aid offer comparison tool that can help families compare college costs and aid packages. The key is to separate free money from money that must be earned or repaid. A large aid offer can still leave a gap if much of it is loans.

Students should also check renewal rules. Some scholarships require a minimum GPA, full-time enrollment, major, service hours, or annual paperwork. A college budget should include what it takes to keep the aid, not just what appears in the first-year offer.

Student and mentor reviewing federal student aid changes and loan planning documents in a college library

Have the Family Money Talk Early

A family money talk works best when everyone knows the purpose: to make the plan visible, not to assign blame. Start with five questions. What can the student contribute from savings or work? What can family contribute each month? Which costs must be paid before classes start? Who will monitor deadlines? What is the backup plan if aid is delayed?

Be specific about timing. Some costs happen before school begins: deposits, placement tests, housing applications, orientation, supplies, transportation, and immunization records. Others repeat monthly: phone, food, transit, medication, laundry, and personal care. A student may have enough aid for tuition but still struggle with the first month of living costs.

Students should leave the conversation with a written plan. It can be a spreadsheet, notes app, or paper worksheet. The format matters less than the decisions: amount available, amount owed, due dates, and who owns each next step.

Build the Student Budget Checklist

A useful college budget has six sections. First, list direct school costs: tuition, fees, housing, meal plan, and required course charges. Second, list learning costs: books, laptop, software, supplies, lab materials, uniforms, or tools.

Third, list transportation: bus pass, gas, parking, rideshare, insurance, repairs, or trips home. Fourth, list daily living costs: food outside the meal plan, toiletries, laundry, phone, medication, childcare, and personal items. Fifth, list one-time setup costs: bedding, winter clothing, dorm supplies, application fees, and deposits. Sixth, list emergency savings, even if the first goal is small.

Scholarships can help with several of these categories when students apply early and stay organized. The iLevelUP Scholarship Sprint guide shows how to turn scholarship work into a short, focused process instead of a last-minute scramble.

Student starts a college list at home using a laptop and notebook.

Plan for Work Without Overloading the Semester

Work can be part of a healthy college budget, but hours matter. A student who needs income should estimate realistic weekly earnings after taxes and transportation. Then compare those hours to class time, study time, commute time, caregiving, and rest.

Work-study is not the same as a grant. Students usually earn it through a job, and the money may arrive through paychecks rather than upfront bill payment. Families should ask the financial aid office how work-study is awarded, how jobs are found, and when the student can expect to be paid.

If the budget depends on work, build a conservative version first. Use lower expected hours, not best-case hours. That protects the student from planning a semester that only works if everything goes perfectly.

How iLevelUP Supports Budget Planning

iLevelUP can help students and support teams turn a college budget into tasks, reminders, and follow-up steps. Instead of telling a student to “figure out money,” the workflow can break the plan into actions: compare aid offers, ask the financial aid office two questions, estimate transportation, update scholarship deadlines, and review the remaining gap.

That structure also helps counselors, TRIO teams, GEAR UP programs, and community partners see where students need support. A budget is most useful when it leads to action before the bill, the move, or the first missed deadline.

Final Takeaway

A college budget gives students a clearer path into the first semester. Start with cost of attendance, compare aid carefully, talk through family contributions, list real living costs, and plan work hours honestly. The earlier families make the money plan visible, the easier it is to choose the right support before stress becomes a crisis.

FAQ: College Budget Planning

What should a college budget include?

A college budget should include tuition, fees, housing, food, books, supplies, transportation, personal expenses, emergency savings, and any one-time setup costs before school starts.

What is cost of attendance?

Cost of attendance is the school’s estimate of total yearly education costs, including tuition and living expenses. It helps colleges calculate financial need and helps families compare schools.

How do families compare financial aid offers?

Compare grants and scholarships first, then work-study, then loans. Subtract true free aid from total costs and look at the remaining gap for each college.

How much should a student work in college?

The right number depends on course load, commute, health, family responsibilities, and financial need. Students should estimate conservatively so work supports college progress instead of replacing study time.

How can first-generation students start budgeting before college?

Start with the college’s cost of attendance, review the aid offer, list monthly living costs, ask family contribution questions, and turn each deadline into a task with a date and owner.

About the Author

Share Article

Related Posts

Two people gathering application papers for small scholarships at a copy center

Small Scholarships: A Calm Plan for 10 Applications

Work toward 10 small scholarships with a flexible plan. Choose good matches, finish two forms at a time, and leave room to rest.
Read Article
Student explores first-gen strengths through guitar practice with a mentor

First-Gen Strengths: Build a Timeline of Your Growth

Find first-gen strengths in three real moments. Build a simple timeline, name your skills, and choose a next step for November 8.
Read Article
Scroll to Top